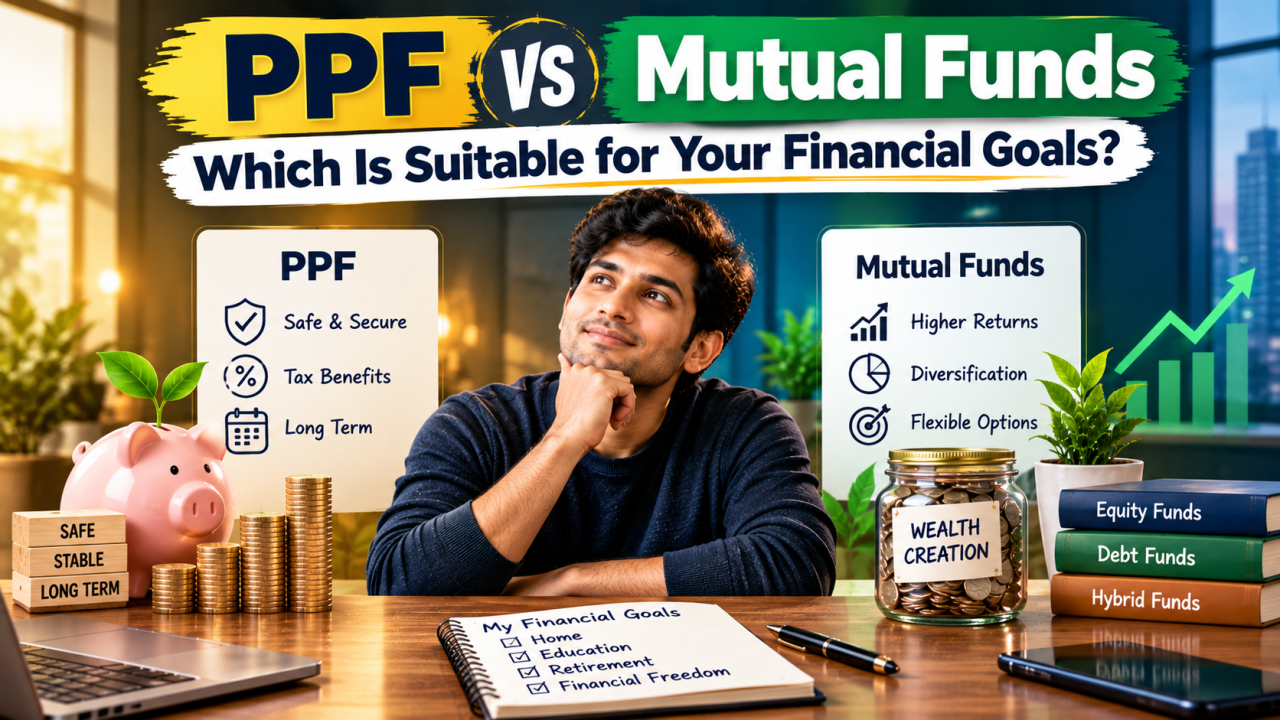
PPF vs Mutual Funds: Which Is Suitable for Your Financial Goals?
Choosing between the Public Provident Fund (PPF) and mutual funds is a common financial decision for people in India.
Both investment options can help you work toward long-term financial goals, but they operate differently.
PPF is a government-backed savings scheme with a long investment horizon, while mutual funds invest in market-linked assets such as stocks, bonds, or a combination of securities.
When comparing PPF vs mutual funds, it is important to understand their returns, risk levels, taxation, liquidity, investment periods, and suitability for different financial goals.
PPF may appeal to people who prefer a structured savings option with government-backed support. Mutual funds may suit investors seeking market exposure and who are willing to accept investment risk.
In this guide, we will explain the key differences between PPF and mutual funds, compare their features, and explore how each option may fit into your financial plan.
1. What Is PPF (Public Provident Fund)?
The Public Provident Fund, commonly known as PPF, is a long-term savings scheme offered by the Government of India.
It is designed to encourage disciplined savings and help individuals build a financial corpus over an extended period.
PPF is generally considered a savings option for people who prioritize capital preservation and long-term financial planning.
The scheme has a long tenure, a government-notified interest rate, and specific rules governing contributions, withdrawals, and extensions.
How Does PPF Work?
When you open a PPF account, you deposit money into the account according to the scheme's rules.
The account earns interest at the rate notified by the government for the relevant period.
The interest rate may change over time, so the return is not necessarily fixed for the entire investment duration.
PPF has a standard maturity period of 15 years, calculated according to the scheme's rules.
After maturity, eligible account holders may choose to withdraw the balance or extend the account under the applicable conditions.
Key Features of PPF
1. Long-Term Savings
PPF is designed for long-term savings.
Its standard maturity period is 15 years, making it more suitable for goals that do not require immediate access to the invested money.
2. Government-Backed Scheme
PPF is a government-backed savings scheme.
This makes it different from market-linked investments such as equity mutual funds.
3. Interest-Based Returns
PPF earns interest at a rate notified by the government.
The applicable rate can change over time, so investors should check the current rate before making investment decisions.
4. Annual Contribution Limits
PPF has minimum and maximum annual contribution limits under the scheme's rules.
Investors should verify the current limits and contribution requirements before opening or funding an account.
5. Tax Benefits
PPF has tax benefits under applicable Indian tax laws.
The availability of deductions and the overall tax treatment depend on the applicable provisions and the investor's tax situation.
6. Withdrawal Restrictions
PPF has specific rules for partial withdrawals, premature closure, and account maturity.
It is not designed for unrestricted access to money.
Who May Consider PPF?
PPF may be worth exploring if you:
- Want a long-term savings option.
- Prefer a government-backed savings scheme.
- Want to build a corpus over an extended period.
- Prefer interest-based returns rather than direct market exposure.
- Can manage the long tenure and withdrawal restrictions.
- Want to understand the tax treatment of a qualifying savings scheme.
PPF may not be suitable for money you need to access immediately or for goals requiring a shorter investment period.
2. What Are Mutual Funds?
A mutual fund is an investment product that pools money from multiple investors and invests it according to a defined investment objective.
The fund is managed by an Asset Management Company (AMC), which invests the pooled money in assets such as:
- Shares of companies
- Government securities
- Corporate bonds
- Money market instruments
- Other permitted financial assets
Each investor owns units of the mutual fund.
The value of these units is represented by the fund's Net Asset Value (NAV), which changes according to the value of its underlying investments and other applicable factors.
Unlike PPF, mutual funds do not offer a single fixed interest rate for all investors.
Their returns depend on the fund category, investment strategy, market conditions, and underlying assets.
Mutual fund returns are market-linked and are not guaranteed.
How Do Mutual Funds Work?
When you invest in a mutual fund, your money is combined with investments from other investors.
The fund uses this money to build a portfolio according to its stated investment objective.
For example:
Suppose you invest ₹10,000 in an equity mutual fund.
Your money becomes part of a portfolio that may hold shares of multiple companies.
If the underlying investments increase in value, the value of your mutual fund units may rise.
If the underlying investments lose value, the value of your units may fall.
The final value of your investment depends on the fund's performance and applicable expenses.
Types of Mutual Funds
Mutual funds are available in several categories, each with different investment objectives and risk profiles.
1. Equity Mutual Funds
Equity mutual funds invest primarily in shares of companies.
They may be considered by investors seeking long-term market exposure who can tolerate fluctuations in investment value.
However, equity funds can experience substantial losses, especially over shorter periods.
2. Debt Mutual Funds
Debt mutual funds invest in fixed-income securities such as government bonds, corporate bonds, and money market instruments.
They may be used for certain income-oriented or short- to medium-term investment needs, depending on the fund's portfolio and risk profile.
Debt funds are not risk-free. They may face interest-rate risk, credit risk, and liquidity risk.
3. Hybrid Mutual Funds
Hybrid mutual funds invest in a combination of asset classes, commonly equity and debt.
Their risk and return characteristics depend on the portfolio's allocation.
4. Index Funds
Index funds aim to track a specific market index by holding securities that represent the index.
They generally follow a passive investment strategy.
Their performance may differ from the index because of expenses and tracking differences.
How Can You Invest in Mutual Funds?
Investors can generally invest in mutual funds through different methods.
Lump-Sum Investment
A lump-sum investment involves investing a larger amount at one time.
For example, you might invest ₹50,000 in a mutual fund in a single transaction.
The value of the investment will depend on the fund's performance after the purchase.
Systematic Investment Plan (SIP)
A Systematic Investment Plan, or SIP, allows you to invest a fixed amount at regular intervals.
For example, you might invest ₹2,000 every month in a mutual fund.
An SIP can help you develop a regular investing habit, but it does not guarantee profits or protect against market losses.
Who May Consider Mutual Funds?
Mutual funds may be worth exploring if you:
- Want exposure to financial markets.
- Have clearly defined investment goals.
- Understand that your investment value can fluctuate.
- Can tolerate the risks associated with the selected fund.
- Want access to professionally managed or index-based portfolios.
- Prefer the flexibility to explore different fund categories.
The suitability of a mutual fund depends on its category, investment objective, risk level, and your financial circumstances.
3. PPF vs Mutual Funds: Key Differences
PPF and mutual funds differ in how they generate returns, how their values change, and how investors can access their money.
The following table summarizes their major differences.
PPF vs Mutual Funds Comparison Table
| Feature | PPF | Mutual Funds |
|---|---|---|
| Investment type | Government-backed savings scheme | Market-linked investment product |
| Returns | Interest rate notified by the government | Depends on the underlying investments |
| Risk | Government-backed savings scheme with defined terms | Varies by fund category and portfolio |
| Return guarantee | Interest is provided according to scheme rules and applicable rates | Returns are not guaranteed |
| Investment period | Standard maturity period of 15 years | Depends on fund type and investor's goals |
| Liquidity | Subject to withdrawal and premature closure rules | Depends on redemption rules and fund type |
| Tax treatment | Offers tax benefits under applicable rules | Depends on fund category, holding period, and tax laws |
| Investment method | Contributions subject to scheme limits | Lump sum or SIP, depending on the fund |
| Market exposure | No direct stock market exposure | Depends on the fund's investment strategy |
| Compounding | Interest accumulates according to scheme rules | Depends on investment performance and reinvestment |
| Suitable goals | Long-term savings and eligible financial goals | Depends on fund category, risk tolerance, and time horizon |
| Withdrawal restrictions | Specific restrictions apply | Lock-in or exit load may apply to certain funds |
Important: PPF and mutual funds are different financial products. PPF offers interest under government-notified scheme rules, while mutual fund returns depend on market performance and are not guaranteed.
4. PPF vs Mutual Funds: Understanding Returns
One of the most common questions investors ask is whether PPF or mutual funds can generate higher returns.
The answer depends on the PPF interest rate over time and the actual performance of the selected mutual fund.
These products have different return structures, so comparing them requires looking at more than just a percentage.
How PPF Returns Work
PPF earns interest at a rate notified by the government.
The applicable rate may change over time.
The amount accumulated in a PPF account depends on:
- The amount contributed.
- The timing of contributions.
- The applicable interest rates over the years.
- The duration of the investment.
- The scheme's interest calculation rules.
PPF is designed for long-term savings, and its interest structure can make it easier to estimate potential account growth when the applicable rates and contribution schedule are known.
However, future interest rates may differ from current rates.
How Mutual Fund Returns Work
Mutual fund returns depend on the performance of the underlying investments.
Equity funds may generate gains when the value of their holdings increases, but they can also experience losses.
Debt funds may generate returns through interest income and changes in the prices of their underlying securities, but they also carry investment risks.
There is no single return rate that applies to all mutual funds.
Illustrative Investment Growth
Suppose you invest ₹1,00,000 for 10 years.
The following table shows how a hypothetical investment value could change under different annual return assumptions.
| Assumed Annual Return | Illustrative Value After 10 Years |
|---|---|
| 5% | ₹1,62,889 |
| 7% | ₹1,96,715 |
| 10% | ₹2,59,374 |
| 12% | ₹3,10,585 |
These figures assume annual compounding at a constant rate and exclude taxes and charges.
They are mathematical illustrations, not forecasts of mutual fund performance or PPF returns.
Actual mutual fund returns may be higher or lower, and the investment may lose value.
PPF returns depend on the interest rates notified over the investment period and the scheme's rules.
What Should You Remember?
PPF provides interest according to government-notified rates and scheme rules.
Mutual funds offer market-linked returns that can fluctuate.
Comparing them only by looking at a potential return percentage can be misleading.
You should also consider risk, liquidity, taxation, investment duration, and your financial goals.
5. PPF vs Mutual Funds: Understanding Risk
Risk is one of the most important factors when comparing PPF and mutual funds.
The two options have different risk profiles and investment characteristics.
Risks Associated With PPF
PPF is a government-backed savings scheme, but investors should still consider several factors.
1. Interest Rate Changes
The interest rate applicable to PPF may change over time.
Future contributions and account growth may therefore be affected by changes in the notified rate.
2. Liquidity Restrictions
PPF has a long tenure and specific withdrawal rules.
Money invested in PPF may not be freely accessible whenever you need it.
3. Inflation Risk
If inflation is higher than the effective return on your savings, the purchasing power of your money may decline.
4. Long Investment Horizon
PPF has a standard maturity period of 15 years.
This long tenure may not suit people who need the money sooner.
Risks Associated With Mutual Funds
Mutual funds can expose investors to different types of risk.
1. Market Risk
The value of a mutual fund can decline when the prices of its underlying investments fall.
Equity-oriented funds are particularly exposed to stock market fluctuations.
2. Interest-Rate Risk
Debt funds holding bonds may experience changes in value when interest rates change.
The impact depends on the fund's portfolio and the characteristics of its securities.
3. Credit Risk
A debt fund may lose value if an issuer fails to meet its financial obligations or its creditworthiness deteriorates.
4. Liquidity Risk
Some securities held by a mutual fund may be difficult to sell quickly at a reasonable price.
The level of liquidity risk depends on the fund's investments and market conditions.
5. Investor Behavior Risk
Frequent buying and selling based on short-term market movements can affect an investor's results.
A clear investment plan can help investors make decisions based on their financial goals rather than short-term market fluctuations.
How Should You Evaluate Risk?
Before choosing between PPF and mutual funds, consider:
- How much loss you can financially tolerate.
- When you will need the money.
- Whether you prefer interest-based savings or market-linked investments.
- Whether you can manage long-term withdrawal restrictions.
- Whether inflation could reduce your purchasing power.
- Whether your investment matches your financial goals.
The right choice depends on your financial needs and ability to handle risk, not simply on the potential return.
All Tools
6. PPF vs Mutual Funds: Tax Benefits and Taxation in India
Taxation is an important factor when comparing PPF and mutual funds.
Both investment options have different tax rules, and the benefits depend on the type of investment and your tax situation.
Tax Benefits of PPF
PPF is commonly known for its tax benefits.
Under the applicable rules, PPF generally follows an Exempt-Exempt-Exempt (EEE) tax treatment.
This means:
- Eligible contributions may qualify for deductions under Section 80C, subject to applicable conditions and the tax regime.
- Interest earned is generally exempt from income tax under the applicable rules.
- Eligible maturity proceeds are generally tax-exempt.
However, deductions under Section 80C are generally available only under the old tax regime, subject to the applicable rules.
Before investing, verify the current tax provisions and eligibility requirements.
Taxation of Mutual Funds
Mutual fund taxation depends on the fund category, holding period, and applicable tax laws.
Equity-Oriented Mutual Funds
Equity-oriented mutual funds are generally subject to capital gains tax when units are sold at a profit.
The applicable tax treatment depends on the holding period and prevailing tax rules.
Short-term and long-term capital gains may be taxed differently.
Debt-Oriented Mutual Funds
Certain debt-oriented mutual funds may be subject to taxation based on the applicable rules for specified mutual fund categories.
The tax treatment can depend on when the investment was acquired and the type of fund.
Tax Comparison
| Tax Feature | PPF | Mutual Funds |
|---|---|---|
| Tax on contributions | Eligible deductions may apply under specific conditions | Depends on the investment and applicable tax provisions |
| Tax on earnings | Interest is generally tax-exempt under applicable rules | Depends on fund category and applicable capital gains rules |
| Tax on maturity or withdrawal | Generally tax-exempt under applicable conditions | Depends on the type of fund and applicable tax rules |
| Tax-saving options | Eligible contributions may qualify under Section 80C | Certain eligible funds may qualify under specific provisions |
| Tax regime considerations | Section 80C benefits generally apply under the old tax regime | Depends on the investment and applicable provisions |
Important: Tax laws can change. Review the current rules before investing and consult a qualified tax professional if you need advice for your circumstances.
7. PPF vs Mutual Funds: Liquidity and Withdrawal Rules
Liquidity refers to how easily you can access your money when you need it.
PPF and mutual funds have different withdrawal conditions.
PPF Withdrawal Rules
PPF has a standard maturity period of 15 years.
However, certain partial withdrawals and premature closure options may be available under specific conditions.
The rules determine when and how much money you can withdraw.
Before opening a PPF account, understand:
- The standard maturity period.
- Partial withdrawal eligibility.
- Premature closure conditions.
- Applicable restrictions and penalties.
- Account extension options after maturity.
PPF is generally not suitable for money you may need immediately.
Mutual Fund Withdrawal Rules
Many open-ended mutual funds allow investors to redeem units on business days, subject to the fund's rules.
However, the amount received depends on the applicable NAV, redemption processing, and any applicable charges.
Some funds have exit loads if you redeem within a specified period.
Certain mutual funds may also have lock-in periods or other restrictions.
Before investing, check:
- Redemption timelines.
- Exit load conditions.
- Lock-in periods.
- Applicable transaction charges.
- Whether the fund has special withdrawal restrictions.
Liquidity Comparison
| Feature | PPF | Mutual Funds |
|---|---|---|
| Access to money | Subject to scheme rules | Depends on fund type and redemption rules |
| Standard investment period | 15 years | Depends on the fund and investor's goals |
| Early withdrawal | Restricted and subject to conditions | Often possible for open-ended funds, subject to rules |
| Withdrawal charges | Depends on applicable scheme conditions | Exit load or other charges may apply |
| Lock-in | Long-term scheme with defined rules | Some funds have lock-in periods |
| Withdrawal value | Depends on account balance and scheme rules | Based on applicable NAV and conditions |
Which Is More Suitable for Emergency Savings?
Emergency savings should generally be kept in an accessible form.
A savings account or another suitable liquid option may be more appropriate for money you may need immediately.
PPF is designed for long-term savings, while mutual fund liquidity depends on the fund category and its redemption rules.
Do not assume that every mutual fund provides instant access without restrictions.
8. What Happens If You Invest ₹1 Lakh in PPF vs Mutual Funds?
A practical comparison can help explain how different investment options work.
Suppose you have ₹1,00,000 and want to invest it for 10 years.
For illustration, consider two hypothetical scenarios:
- PPF: An assumed annual interest rate of 7.1%, remaining unchanged for the entire period.
- Mutual fund: An assumed annual return of 10%, compounded annually.
These rates are illustrative assumptions, not current investment offers or expected mutual fund returns.
Estimated Value After 10 Years
| Investment Option | Initial Investment | Assumed Annual Rate | Illustrative Value After 10 Years |
|---|---|---|---|
| PPF | ₹1,00,000 | 7.1% | Approximately ₹1,98,385 |
| Mutual fund | ₹1,00,000 | 10% | Approximately ₹2,59,374 |
These figures assume annual compounding and exclude taxes, fees, and other charges.
The PPF example assumes the interest rate remains unchanged for the entire period. Actual PPF account growth depends on the notified rates, contribution timing, and scheme rules.
The mutual fund example is a mathematical illustration only. Actual returns may be higher or lower, and the investment may lose value.
What Does This Comparison Show?
The example demonstrates how different assumed rates of return affect the final value of an investment.
It does not establish that mutual funds will outperform PPF.
The actual outcome depends on:
- PPF interest rates over time.
- Mutual fund market performance.
- Investment duration.
- Contribution timing.
- Applicable expenses and taxes.
When comparing investments, consider both potential returns and the risks involved.
9. Advantages and Disadvantages of PPF
PPF is a long-term savings scheme with defined rules and government-backed support.
However, it also has limitations that investors should understand.
Advantages of PPF
1. Government-Backed Savings Scheme
PPF is backed by the Government of India and follows defined scheme rules.
This makes it different from market-linked investments.
2. Tax Benefits
Eligible PPF contributions and earnings may receive tax benefits under applicable rules.
The tax treatment can make PPF relevant for certain long-term savings goals.
3. Interest-Based Returns
PPF earns interest at a rate notified by the government.
The rate may change over time, but the account follows the scheme's interest calculation rules.
4. Long-Term Savings Discipline
The long tenure can encourage regular saving for future financial needs.
5. No Direct Stock Market Exposure
PPF does not expose the account balance directly to stock market fluctuations.
This may appeal to people who prefer a structured savings option.
Disadvantages of PPF
1. Long Maturity Period
PPF has a standard maturity period of 15 years.
This may not suit people who need their money sooner.
2. Withdrawal Restrictions
Partial withdrawals and premature closure are subject to specific conditions.
The account is not designed for unrestricted access.
3. Interest Rate Changes
The government-notified interest rate may change over time.
Future returns may therefore differ from those calculated using the current rate.
4. Contribution Limits
PPF has annual contribution limits under the scheme's rules.
This may limit how much you can invest through the account.
5. Inflation Risk
If inflation exceeds the effective return on savings, purchasing power may decline.
10. Advantages and Disadvantages of Mutual Funds
Mutual funds provide access to different financial markets and investment strategies.
However, they also involve risks that investors should understand.
Advantages of Mutual Funds
1. Diversification
Many mutual funds invest in multiple securities.
Diversification can reduce the impact of poor performance by an individual holding, although it cannot eliminate investment risk.
2. Flexible Investment Amounts
Some mutual funds allow investors to begin with relatively small amounts.
SIPs can help investors contribute regularly instead of investing a large sum at once.
3. Multiple Investment Categories
Investors can choose among equity, debt, hybrid, index, and other fund categories, depending on their goals and risk tolerance.
4. Professional Management
Actively managed mutual funds are managed by investment professionals who make decisions according to the fund's stated strategy.
Index funds generally follow a passive approach designed to track a particular index.
5. Potential for Long-Term Growth
Certain mutual funds may offer opportunities for long-term growth.
However, returns are not guaranteed, and losses are possible.
Disadvantages of Mutual Funds
1. Market Risk
The value of mutual fund investments can fluctuate.
Investors may receive less than the amount they invested.
2. No Guaranteed Returns
Mutual funds do not generally promise a fixed return.
Their performance depends on the underlying investments.
3. Expenses
Mutual funds charge expenses that affect investor returns.
Review the expense ratio and other applicable charges.
4. Complexity
Different mutual fund categories have different risk profiles and investment strategies.
Beginners may need time to understand these differences.
5. Tax Considerations
Tax treatment depends on the type of fund, holding period, and applicable tax rules.
Investors should understand the relevant tax implications before investing.
11. PPF vs Mutual Funds: Which Is Suitable for Different Financial Goals?
The suitability of PPF and mutual funds depends on what you want to achieve with your money.
Different goals require different time horizons and levels of risk tolerance.
For Retirement Planning
PPF may be considered for long-term savings because of its defined structure and government-backed support.
Certain mutual funds may also be considered for long-term market exposure, depending on the investor's risk tolerance and financial plan.
Retirement planning may involve multiple investment products rather than relying on a single option.
For Children's Education
If you are saving for a child's education, consider when the money will be needed.
PPF may suit certain long-term savings goals, but its maturity and withdrawal rules should be considered carefully.
Mutual funds may offer market exposure, but their suitability depends on the investment horizon and risk tolerance.
For Long-Term Wealth Building
Some investors consider equity-oriented mutual funds for long-term market exposure.
However, these funds can experience substantial losses and do not guarantee returns.
PPF may also form part of a long-term savings plan for investors who prefer a government-backed scheme.
For Tax Planning
PPF may offer tax benefits under applicable provisions.
Certain mutual funds may also qualify for specific tax benefits, subject to the applicable rules.
Your tax regime and financial circumstances should be considered before making a decision.
Financial Goal Comparison
| Financial Goal | Factors to Consider |
|---|---|
| Retirement savings | Time horizon, risk tolerance, and income needs |
| Children's education | When the money is needed and the amount required |
| Long-term wealth building | Investment risk, diversification, and time horizon |
| Tax planning | Eligibility for deductions and applicable tax rules |
| Emergency savings | Accessibility and withdrawal restrictions |
| Long-term disciplined savings | Contribution limits, maturity, and account rules |
No single investment option is suitable for every financial goal.
12. How to Choose Between PPF and Mutual Funds
Before deciding where to invest, ask yourself a few practical questions.
1. When Will You Need the Money?
Your investment horizon can influence which products are appropriate.
PPF has a long maturity period, while mutual fund investment periods depend on the fund and your goals.
Money needed soon may require a different approach.
2. How Much Risk Can You Handle?
Consider whether you can tolerate fluctuations or potential losses.
If a decline in investment value would seriously affect your financial situation, carefully assess the risks before investing in market-linked products.
3. Do You Prefer Interest-Based Savings or Market-Linked Growth?
PPF offers interest according to government-notified rates and scheme rules.
Mutual funds provide market-linked returns that depend on the underlying investments.
Consider which structure aligns with your financial needs.
4. How Important Is Liquidity?
PPF has withdrawal restrictions.
Mutual fund liquidity depends on the fund's category and redemption rules.
Check how quickly you can access your money and whether any restrictions apply.
5. What Is Your Tax Situation?
Compare the tax implications of each option.
PPF may offer tax benefits under applicable rules, while mutual fund taxation depends on the fund category and holding period.
6. Have You Built Emergency Savings?
Before investing money for long-term goals, consider whether you have enough accessible savings to handle unexpected expenses.
A Simple Decision Framework
| If Your Priority Is... | Consider Evaluating... |
|---|---|
| Government-backed long-term savings | PPF |
| Market-linked investment growth | Mutual funds suited to your goals and risk tolerance |
| Tax benefits under eligible provisions | PPF and other qualifying investments |
| Flexible investment methods | Mutual funds offering suitable lump-sum or SIP options |
| Long-term disciplined savings | PPF or suitable mutual fund investments, depending on your needs |
| Easy access to emergency money | Accessible savings options with suitable withdrawal terms |
These are general considerations, not personalized investment recommendations.
13. Can You Invest in Both PPF and Mutual Funds?
Yes. Some investors use both PPF and mutual funds as part of their overall financial plan.
The two products serve different purposes and have different risks.
For example, an investor may use PPF for long-term savings while investing in mutual funds for market-linked investment goals.
The proportion allocated to each depends on:
- Financial goals.
- Investment horizon.
- Risk tolerance.
- Income and expenses.
- Emergency savings.
- Tax considerations.
Example of a Hypothetical Allocation
Suppose someone has ₹2,00,000 available for investment after covering essential expenses and emergency savings.
They might explore a hypothetical allocation such as:
| Investment Type | Amount |
|---|---|
| PPF | ₹1,00,000 |
| Mutual funds | ₹1,00,000 |
| Total | ₹2,00,000 |
This is only an illustration, not a recommended allocation.
PPF contributions are subject to scheme limits, and mutual fund investments carry market risk.
The actual allocation should reflect the investor's financial circumstances, risk tolerance, and goals.
The key is to understand what each investment does and how it fits into your overall financial plan.
Conclusion: PPF vs Mutual Funds — Which Is Suitable for Your Financial Goals?
Choosing between PPF and mutual funds depends on your financial goals, investment horizon, risk tolerance, and liquidity needs.
The Public Provident Fund (PPF) is a government-backed savings scheme designed for long-term savings. It offers a government-notified interest rate and tax benefits subject to applicable rules. However, it has a 15-year maturity period and restrictions on withdrawals.
Mutual funds provide access to different asset classes, including equity, debt, and hybrid investments. They can help investors work toward goals such as retirement planning, education funding, and long-term wealth creation. However, returns are not guaranteed, and market-linked funds carry investment risk.
If you prioritize government-backed savings and a long-term investment structure, PPF may suit your needs.
If you are comfortable with market fluctuations and want exposure to different asset classes, mutual funds may be worth considering.
You can also use both options as part of a diversified financial plan, depending on your goals and financial situation.
Ultimately, the right choice is the one that aligns with your financial priorities, investment timeline, and comfort with risk.
Plan Your Investments According to Your Financial Goals
Before choosing between PPF and mutual funds, take time to understand your financial goals and investment timeline.
Ask yourself:
- What am I investing for?
- When will I need the money?
- How much investment risk can I comfortably accept?
- Will I need access to my money before the investment matures?
- Which tax rules apply to my situation?
Start with a clear financial goal, choose investments that match your needs, and review your plan periodically.
Explore more personal finance guides to learn about saving, investing, and building a financial plan.
Disclaimer: This article is for educational purposes only and should not be considered personalized financial advice. Investment decisions should be based on your individual circumstances.
Frequently Asked Questions (FAQs)
1. What is the main difference between PPF and mutual funds?
PPF is a government-backed savings scheme with a government-notified interest rate, while mutual funds invest in assets such as stocks, bonds, or a combination of investments. Mutual fund returns depend on market performance and are not guaranteed.
2. Is PPF better than mutual funds?
Neither option is universally better. PPF may suit people seeking long-term savings with government-backed protection, while mutual funds may suit investors who are comfortable with market risk and want exposure to different asset classes.
3. Are PPF returns guaranteed?
PPF is a government-backed scheme, and its interest rate is notified by the government. The rate may change over time, so future returns should not be assumed to remain at the current rate.
4. Are mutual funds riskier than PPF?
Market-linked mutual funds carry investment risk, and their values can rise or fall. PPF is a government-backed savings scheme and does not have the same market-linked risk, although its interest rate can change.
5. Is PPF tax-free in India?
PPF generally enjoys exempt-exempt-exempt (EEE) tax treatment under applicable rules. Tax benefits and deductions depend on the prevailing tax laws and the investor's eligibility.
6. Can I withdraw money from PPF before 15 years?
PPF has specific rules for partial withdrawals and premature closure. Withdrawals are subject to eligibility conditions, lock-in requirements, and applicable scheme rules.
7. Can I invest in both PPF and mutual funds?
Yes. Investors can use both options as part of a financial plan. PPF can serve long-term savings goals, while mutual funds can provide exposure to different asset classes based on the investor's risk tolerance.
8. Which is more suitable for long-term wealth creation: PPF or mutual funds?
The suitability depends on the investor's goals and risk tolerance. PPF offers government-backed savings, while equity mutual funds provide market-linked growth potential but can also experience losses.
9. Are mutual fund returns guaranteed?
No. Mutual fund returns are not guaranteed. Their performance depends on the underlying investments and market conditions. Investors should understand the risks associated with the selected fund.
10. How should I choose between PPF and mutual funds?
Consider your financial goals, investment horizon, risk tolerance, liquidity requirements, and tax situation. Compare the features of both options and choose according to your individual needs.